Public sector productivity – not an oxymoron

Yesterday I attended a fascinating event at the LSE, the launch of [amazon_link id=”0857934988″ target=”_blank” ]Growing the Productivity of Government Services[/amazon_link] by Patrick Dunleavy and Leandro Carrera – the video is due to go online later. I’ve only read about half the book so this post is more about the event than a review. Even at this stage, though, it’s clearly an essential read for anybody concerned with the quality, efficacy and value for money of the public sector. That’s all of us, of course: 24% of UK GDP is accounted for by public services, so productivity growth here is vital for economic growth overall; and we are all consumers of public services, from defence and justice to schools and rubbish collection.

[amazon_image id=”0857934988″ link=”true” target=”_blank” size=”medium” ]Growing the Productivity of Government Services[/amazon_image]

In his introductory talk, Prof Dunleavy noted the variation between different public sector organisations in the measures of productivity they had been able to collect. Spending on ICT was positively correlated with improvements, despite the well-known IT disasters, because the technology is an important enabler of changed ways of working. Reorganisations are also linked to productivity improvements (although spending on external management consultants not at all). He concluded that the key steps for achieving productivity improvements are: the leaders of the organisation must engage with change; the agency must develop its own ideas for innovation; the leadership must engage with employees and ensure they don’t believe change is only about saving costs and cutting jobs; and intra-government and 3rd sector rivalry is helpful. The book includes many practical specific examples of change, successful and not, in different (national) government organisations, and also a really helpful table of suggestions with comparable private sector examples.

The terrific thing about the book – as one of the panellists, Barry Quirk, CE of Lewisham Council underlined – is that it fills the empty territory between the abstractions of ‘policy’ and the rough and tumble of politics by looking at organisations and the specifics of what they can do to improve. His main message was about needing ‘productivity with a purpose’ and never losing sight of what the public service purpose of the organisation is. As he pointed out, among the most borrowed titles from Lewisham’s libraries are a guide to pubs in South London, one to teenage sex, and 50 Shades of Grey – along with, thank goodness, Hilary Mantel’s [amazon_link id=”0007315090″ target=”_blank” ]Bring Up The Bodies[/amazon_link].

[amazon_image id=”0007315090″ link=”true” target=”_blank” size=”medium” ]Bring Up the Bodies[/amazon_image]

Joe Grice, chief economist at the Office for National Statistics said productivity improvements were imperative not so much because of public finances – although that obviously matters – but because people value public services so highly. He emphasised the need to link measures of productivity to activities so there is a feedback loop.

Edwin Lau, head of the OECD’s public sector productivity group, said Ministries of Finance tend to be most interested in the subject because they want to harvest the financial savings, but it is important for public agencies to appreciate the scope productivity improvements give them for internal reallocation of funding to serve their strategic aims; and that officials in different countries could learn more from each other.

This gave rise to one comment from a US member of the audience, noting that many of his compatriots would consider ‘public sector productivity’ an oxymoron, and the book would need to be retitled something like ‘Lifting the burden of the public sector on Americans’ in his country! The discussion left me feeling optimistic, however. As a senior official in the audience said to me afterwards, many people think improving public sector productivity is just too hard, but it can be done.
The unknown robber barons

In today’s Financial Times, Edward Luce points out that the US – creator of the internet – has dropped from top in the late 1990s to 16th now in the OECD league for average internet speeds, and has some of the highest prices too. He notes that South Koreans speak of trips to the US as ‘internet holidays’, so unfavourably does the experience compare with online access back home. Given the rise of Samsung – which spends more than twice as much proportionately on R&D as Apple (5.7% vs 2.2% of revenues respectively) – it can only be a matter of time before online leadership migrates decisively to Asia.

The article is clear about the problem – the Comcast monopoly, and the donations the company makes to Barack Obama, along with its enormous lobbying effort. Comcast’s senior VP David Cohen is apparently one of the US President’s biggest fundraisers. Comcast spent more than $14m on lobbying in 2011, making it the ninth biggest spender in the US.

This only confirms the argument of Susan Crawford’s book [amazon_link id=”0300153139″ target=”_blank” ]Captive Audience: The Telecom Industry and Monopoly Power in the New Gilded Age[/amazon_link], which directly compares Comcast to the giant trusts of the late 19th century, broken finally by the struggle to implement the 1890 Sherman Anti-Trust Act. I have to say the book isn’t the most exciting read in the world – not as enthralling as Tim Wu’s [amazon_link id=”1848879865″ target=”_blank” ]The Master Switch[/amazon_link] – but nevertheless it does a superb job of depicting Comcast’s strategy. It emerges as a superbly well-run business in strategic terms – although not, it seems, for customer service.

The company has been particularly astute about its engagement with Congress and regulators, and in judging the technological trajectory of the industry. However, the book also explains why and how the FCC made the decisions that now look mistaken, and is therefore a rare instance of insight into the complexities and compromises of the official and political world. This is much more useful than playing the blame game. So though there may be more US-centric detail than the general reader wants, this is an essential book for anyone interested in communications markets and digital convergence. I have to admit I’d heard of Comcast, but not at all of its controlling and founding family, the Roberts pere et fils, the unknown “robber barons” of the new gilded age.

[amazon_image id=”0300153139″ link=”true” target=”_blank” size=”medium” ]Captive Audience: The Telecom Industry and Monopoly Power in the New Gilded Age[/amazon_image]

Apparently Susan Crawford is a candidate for the post of next head of the FCC, but the book attacking the Comcast monopoly is seen to have damaged her chances. On the other hand, President Obama doesn’t need re-electing, so maybe he will be brave and nominate a candidate with the interests of American consumers at heart – I was staggered to read in Crawford’s book that the average user pays $143 a month for their high-speed internet and cable bundles.

For here is another example of the way big business has bought political power, and therefore the freedom to make still more money and buy still more power, in America. That subversion of social welfare in the interests of the rich affects the rest of the west too, not to mention cementing the future economic and geo-political strength of Asia.

A modest proposal (involving digital market dynamics)

One of the best books about the effect of digital technology on business dates from 1999. [amazon_link id=”087584863X” target=”_blank” ]It’s Information Rules: A Strategic Guide to the Network Economy[/amazon_link] by Carl Shapiro and Hal Varian (now chief economist at Google). Until recently, I’ve thought it didn’t need updating, for although the examples are obviously dated, the principles are not.

[amazon_image id=”087584863X” link=”true” target=”_blank” size=”medium” ]Information Rules: A Strategic Guide to the Network Economy[/amazon_image]

However, a couple of excellent recent books on the telecommunications and media sector have made me start to wish for an update of Information Rules. They are Timothy Wu’s [amazon_link id=”1848879865″ target=”_blank” ]The Master Switch: The Rise and Fall of Information Empires[/amazon_link] and Susan Crawford’s new book, [amazon_link id=”0300153139″ target=”_blank” ]Captive Audience: The Telecom Industry and Monopoly Power in the New Gilded Age.[/amazon_link] Telecoms is obviously a network industry, with the characteristic kind of increasing returns to scale you get with networks.

[amazon_image id=”1848879865″ link=”true” target=”_blank” size=”medium” ]The Master Switch: The Rise and Fall of Information Empires[/amazon_image]

[amazon_image id=”0300153139″ link=”true” target=”_blank” size=”medium” ]Captive Audience: The Telecom Industry and Monopoly Power in the New Gilded Age[/amazon_image]

Both these newer books are excellent on the sector. What I’d like is an update – beyond the one chapter in the 1999 edition of Shapiro and Varian – on business strategy and market dynamics (including two-sided aspects) in network markets. For digital connectivity is making the network aspect more prominent in other sectors. Finance is obviously one, but there are more sectors where digital technologies are enabling new forms of intermediation as well as disintermediating old forms, where there are information asymmetries or experience goods, and where access to new platforms is becoming vital. Consider publishing, or indeed even retailing – say a new fashion designer facing a declining physical high street.

So here’s a modest proposal: please will somebody write about these new market dynamics (and the competition and distributional implications) where we need two-sided market models, increasing returns and non-linearities, and the experience good/public good characteristics taken into account?!

Digital jobs – or not?

As always, John Naughton’s weekend column was very interesting – this week’s theme was Digital capitalism produces few winners. It contrasts the profit of the digital titans – Apple, Amazon, Google – with the relatively few jobs and poor working conditions they offer. Amazon in the UK (where the digital companies are already in the public stocks over their tax practices) was the subject of an eye-opening FT feature recently, Amazon unpacked.

John Naughton’s column starts: “Need a crash course in digital capitalism? Easy: you just need to understand four concepts – margins, volume, inequality and employment. And if you need more detail, just add the following adjectives: thin, vast, huge and poor.” This is in the same vein as Brynjolfsson and McAfee’s [amazon_link id=”0984725113″ target=”_blank” ]Race Against the Machine[/amazon_link] which argues that the new technologies are economising on human labour, and Paul Krugman’s recent Rise of the robots column, noting that manufacturers are investing in capital-intensive facilities, so productivity is high and the need for labour low.

[amazon_image id=”0984725113″ link=”true” target=”_blank” size=”medium” ]Race Against the Machine: How the Digital Revolution is Accelerating Innovation, Driving Productivity, and Irreversibly Transforming Employment and the Economy[/amazon_image]

I would sound some notes of caution about this ‘the robots are eating all the jobs’ trope. One, this is the stage of the business cycle when jobs gloom is at its most intense – remember the New York Times special book, [amazon_link id=”0812928504″ target=”_blank” ]The Downsizing of America[/amazon_link], published in 1992 just ahead of the long upturn and employment boom? Two, the only way to assess the impact of new technologies is to look at aggregate data, not just a few firms – the distribution of income data suggest there is indeed something in the story about capital intensity and productivity, but the US employment ratio has been rising gently, albeit well below pre-crisis levels still. Three, there is a question about how informative existing data are – Mike Mandel’s work on the data-driven economy is suggestive of significant gaps in our knowledge.

[amazon_image id=”0812928504″ link=”true” target=”_blank” size=”medium” ]The Downsizing of America[/amazon_image]

Finally, the most productive sectors of the economy are always making jobs disappear, and there is a period of uncomfortable adjustment, including in the wage distribution, until jobs reappear in less productive sectors of the economy. Nobody has yet convinced me there’s anything different about the digital economy in this regard, although Krugman’s second ‘robots’ column on oligopoly power, Robots and Robber Barons, certainly flags up a serious issue. For me, the best book on the impact of digital on jobs remains Levy and Murnane’s [amazon_link id=”0691124027″ target=”_blank” ]The New Division of Labour: How Computers Are Creating the Next Job Market[/amazon_link], although it’s a few years old now.

[amazon_image id=”0691124027″ link=”true” target=”_blank” size=”medium” ]The New Division of Labor: How Computers Are Creating the Next Job Market[/amazon_image]

Where *do* banks get their money?

Yesterday I attended an interesting session trying to identify specific reforms to the banking system – competition policy, regulatory change, consumer-facing advice and so on – run by the Finance Innovation Lab. The event ran under the Chatham House Rule so I can’t be specific about who said what. There were some very thoughtful comments, however.

– there are large (private) economies of scale in finance but large (social) diseconomies of scale. How should competition and other policy interventions change to reflect the latter?

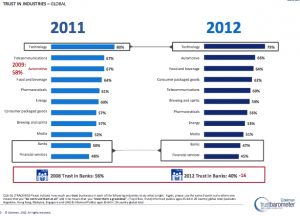
– financial services lies at the bottom of the Edelman trust barometer, tech companies at the top. Why this contrast, when finance is also an IT-intensive information business – what does it tell us about finance?

Edelman – trust in industries

– is low trust an opportunity to bring about change?

– the big incumbent UK banks simply can’t lend to SMEs as they’re too big. If Lloyds wants to grow its £1 trillion balance sheet by a modest 5% a year, it will be looking to lend to hedge funds, not people or small businesses.

– the cost of financial intermediation has not fallen despite the growth in the finance sector; Thomas Philippon’s paper ‘Has the US finance industry become less efficient?’ was cited.

I can talk about my own contribution, which was my usual riff about competition: UK (retail) banking is not a ‘market’ as there is no entry and no exit, only failed or unprofitable new entrants; the incumbent UK banks’ back-book of inert deposits combines with other barriers to make entry impossible, and they might need to be broken up, not just into retail and investment banks, but into smaller units altogether; banking is the only dinosaur industry not yet made extinct by digital disruption, but it’s ripe for this – if only regulators will make it possible for new technology-based entrants with entirely different business models. I’m not wildly optimistic about this. The regulators know this in principle but they don’t have the understanding or staff or contact with new start-ups to enable it.

Another speaker was Professor Richard Werner of Southampton University, whose contribution I can describe because he’s published it in [amazon_link id=”1908506237″ target=”_blank” ]Where Does Money Come From? A Guide to the UK Monetary and Banking Sytem[/amazon_link]. He  talked persuasively of the need for regional or local institutions with detailed knowledge of local businesses. He also quite rightly pointed out that almost nobody understands money, not least because all the textbooks he has ever looked at get it wrong (I agree!). I didn’t buy his argument for centralised, state-owned money creation. But I’ll read his essay in the book to give the argument a chance.

[amazon_image id=”1908506237″ link=”true” target=”_blank” size=”medium” ]Where Does Money Come From?: A Guide to the UK Monetary & Banking System[/amazon_image]