Christmas thoughts on consumerism

I didn’t know what to make of [amazon_link id=”0465021867″ target=”_blank” ]Against Thrift: Why Consumer Culture is Good for the Economy, the Environment and Your Soul [/amazon_link]by James Livingston. Reading it was like being on the receiving end of an argument you don’t understand – there’s no mistaking the author’s passion and eloquence but not enough common terrain for a debate.

The subtitle and blurb make it clear that the book aims to be contrarian, and made me think I was getting a counter-blast against government austerity measures to cut the deficit. But it’s actually an argument with the author’s perception of economic growth theory. As far as I understand it (and I could have completely misunderstood), his argument is that the conventional wisdom is that investment in capital is what determines the economy’s rate of growth, that investment requires saving, and that people are therefore constantly urged to be thrifty. Moreover, this fits in with their natural “powerful psychological urge to put their desires on hold…. Because everyone knows how and why to defer gratification.” (page xi) However, growth depends actually on consumption not on investment, and in fact the net private investment in the US (as measured by net private capital formation in the National Income and Product Accounts) has been in decline for a century while massive economic growth has still occurred. Prof Livingston also has a cultural gripe about thriftiness: he sees the habit of thrift as a “soul-crushing emotional trap as well as an economic dead end”.

Part of my problem in assessing this is the author, a Professor of History at Rutgers University, draws on Marxist theory, which I’ve never studied. Some parts of the argument seem to make perfect sense. The purpose of economic growth is to enable people to improve their welfare by consuming goods and services in greater amounts and variety, as they desire. So I completely agree that consumption is all-important, and that much economic debate – and especially economic policy – has mercantilist instincts and focuses too much on producer interests. Besides, every economist knows GDP growth rests on consumption growth because that’s about two-thirds of the total. Henry Ford is celebrated for appreciating that the workforce needed to be paid enough to consume in order to create a mass market. It has also become a commonplace in many circles now to note that the profit share of income has increased to new peaks compared to the labour share and – pace Henry Ford – this is not a good thing at all.

But other parts of Prof Livingston’s argument are bewildering. For one thing, one of the many lessons of behavioural economics (and daily experience) is that frankly most people have no ability to defer gratification. Economists and psychologists have written extensively about this, and on the need for commitment devices if anyone is every to diet successfully or not over-spend on their credit card or save enough for their retirement.

And then there’s the claim that conventional theory says growth depends above all on investment. Just to make sure I wasn’t losing my mind, I turned back to the standard growth text, Aghion and Howitt on the [amazon_link id=”0262012634″ target=”_blank” ]Economics of Growth[/amazon_link], to confirm that as I thought innovation is seen as the key to growth, albeit embedded in either people’s minds (human capital) or delivered by innovating businesses (tangible and intangible capital). This was true empirically in the heyday of Solow’s neoclassical growth model – all the action was in the technical change term rather than the growth of labour or investment in capital. It’s also now true in standard modern growth theory. The textbook explores this broadly – there are chapters on competition and entry, on institutions, on education, on finance, on trade, on democracy, and on culture. The recent empirical work on growth accounts for it in terms of investment in both human and physical capital but also in terms of the productivity of each and multi-factor productivity. So where does the book’s emphasis on investment (especially as measured in the national accounts) come from? And how does Livingston square his dismissal of the supposed focus on investment with his demolition of the advertising industry which aims to make us spend rather than save?

Despite my bewilderment, I very much enjoyed the sections of the book where Livingston takes on the AdBuster, culture jamming types. This played to my prejudice that clever cultural disdain for consumerism is a rather snobbish attitude on the part of affluent people who are just as consumerist as the rest of us but spend their money on upmarket rather than mass market products and pastimes. The author here focuses on the culture of consumerism. describes the part played by the consumption of western rock music influences – in the shape of the magnificent Plastic People of the Universe – in Czechoslovakia’s Charter 77 and Velvet Revolution. He concludes: “Advertising sells freedom, expands consciousness, and heralds new values in another strange way, by sponsoring a critique of consumer culture from within the precincts of commodity fetishism.” (p131) Its self-references make consumers question their own preferences, he argues.

In the end, though, I had to stop reading the book. It exasperated me too much. I’d like somebody else to read it please, and explain what I’m missing. Meanwhile, it’s time to do some online sales shopping….

[amazon_image id=”0465021867″ link=”true” target=”_blank” size=”medium” ]Against Thrift[/amazon_image]
The perfect present

One of my all-time favourite books is a slim volume of essays by Anne Fadiman, [amazon_link id=”0140283706″ target=”_blank” ]Ex Libris[/amazon_link]. It’s a book about books.

[amazon_image id=”0140283706″ link=”true” target=”_blank” size=”medium” ]Ex Libris: Confessions of a Common Reader[/amazon_image]

Although this passage in the final essay, Secondhand Prose, is about a birthday and not Christmas (and is hardly to do with economics at all – non-pecuniary utility, maybe?), it speaks volumes about how to choose the perfect present:

“On the morning of my forty-second birthday, George informed me that I was about to be spirited to a mystery destination. I followed him to the subway. We got off at Grand Central Station, where he commanded me to stand at a discreet distance during his sotto voce procurement of two round-trip tickets to somewhere. After a half-hour’s ride through the Bronx and Yonkers, we disembarked at a town called Hastings on Hudson. What could possibly await us here? A three-star restaurant? A world-class art collection? A hot-air balloon, stocked with a magnum of Veuve Cliquot and a pound of caviar, from which we would achieve a hawk’s eye view of the Hudson Valley?…Then I saw it: a weather-beaten little shop, perched on such a declivitous slope that it looked in danger of sliding into the Hudson River, with a faded blue sign over the door that said BOOKSTORE. Inside were an unkempt desk, a maze of out-of-plumb shelves and 30,000 used books.

“Seven hours later, we emerged from the Riverrun Bookshop carrying nineteen pounds of books. (I weighed them when we got home.)

“Now you know why I married my husband.”

Of course, nobody will be so foolish as to buy me a Kindle this Christmas….

In St Malo


Mince pies and the crisis of capitalism

Times being what they are, there was something enticing about a book titled [amazon_link id=”0674055748″ target=”_blank” ]The Crisis of Capitalist Democracy[/amazon_link]. By Richard Posner, no less, co-host of the always thought-provoking and often illuminating Becker-Posner blog. I should have been alerted by the praise on the back cover – “not exactly beach reading”, “notable for its high seriousness” – to the fact that this probably was not a good choice for the start of mince pie season. So I’m not at all sure that I’ll do it justice here.

The book, published in 2010, offers an analytical overview of the causes of the Great Financial Crisis and the subsequent depression, and traces some of the likely political consequences. The first section, the analytical narrative of events from 2001 to 2009, is extremely dense, and I speak as one who revels in reading economics papers. To put 250 pages in a nutshell, Posner pins much of the blame on Alan Greenspan and Ben Bernanke for creating the macroeconomic environment for asset price bubbles, essentially for ideological reasons in his view; and then on Hank Paulson and the US Treasury for their inconsistency in not bailing out Lehman Brothers in the autumn on 2008. (The book is entirely US-focussed.) Those mistakes having been made, it’s not clear what actions he thinks the authorities ought to have taken but didn’t, as the book rules out most possibilities including that chosen by the UK authorities, of direct government stakes in troubled banks, or the earlier Swedish option of separating troubled assets into a ‘bad bank’. Posner is particularly critical of President Obama for not having a plan when he assumed office despite the several months of transition. The message, Posner concludes, was that either the incoming Administration was as incompetent as its predecessor, or that nobody had any idea what to do.

Despite the mass of detail in this section, including 12 pages on the rescue of GM and Chrysler, it feels strikingly incomplete. There is no mention of the international dimensions of the financial crisis at all. While this book focuses on the American efforts to reform finance and the links between economic policy and US politics, this omission is surely a flaw. Still, the discussion in the second and third parts of the book does have universal interest.

Part two concerns the ideas we bring to understanding and resolving the crisis – the renewed lesson about the pervasiveness of true uncertainty, the revival of ‘Keynesian’ ideas (some more closely linked to Keynes’s writing than others), the fatally flawed model of efficient financial markets and the weaknesses of macroeconomics. He particularly cites Akerlof and Shiller on [amazon_link id=”069114592X” target=”_blank” ]Animal Spirits[/amazon_link]. Who could at this point in history disagree with Posner’s conclusion that macroeconomics needs to embrace both psychology and political science?

The third part, relatively brief, is the most interesting. Posner turns to the politics of economic and regulatory reform. He is not optimistic about the capacity of the US political system to achieve – well, anything, in fact. Again, hard to disagree (as a Robin Harding column about the current state of budget negotiations from today’s FT underlines). The legacy of the banking crisis – he agrees here with [amazon_link id=”0691142165″ target=”_blank” ]Reinhardt and Rogoff [/amazon_link]- is greater public debt. Posner describes US politics as “cumbersome, clotted, competence-challenged and even rather shady” (p387), able to respond to a true emergency (hmmmm, I think back to [amazon_link id=”0241950856″ target=”_blank” ]Hurricane Katrina [/amazon_link]and wonder) but not to continuing huge challenges. Populism won’t help, but populism we got. The inability to address the public debt and structural, growing deficits, is the crisis of American capitalist democracy.

[amazon_image id=”0674055748″ link=”true” target=”_blank” size=”medium” ]Crisis of Capitalist Democracy[/amazon_image]

The economy’s most important asset: you

The Office for National Statistics has just published a really interesting new paper estimating the size of the UK’s capital stock. The figure (£17.12 trillion in 2010) depends on certain assumptions – more on those below – but one key point is the general scale. That’s two and a half times the size of the country’s physical capital stock. Even varying the assumptions generates estimates larger than the value of all the factories, machines, vehicles etc.

No wonder both the theory and evidence (see for example Barro and Salai-i-Martin in [amazon_link id=”0262025531″ target=”_blank” ]Economic Growth[/amazon_link]) find human capital to be vital for economic growth. Although the importance of ‘education, education, education’ has become a commonplace, its role in the productive capacity of the economy is given much greater weight when you appreciate just how significant in scale the human capital stock is.

[amazon_image id=”0262025531″ link=”true” target=”_blank” size=”medium” ]Economic Growth[/amazon_image]

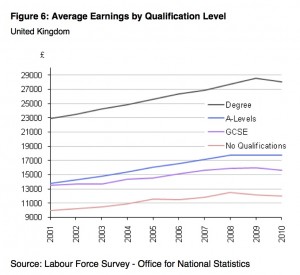
Interestingly, the paper estimates that the UK’s stock of human capital declined in 2010 due to the downturn. This is an effect of recession that has to be factored into any view about the productive capacity of the economy when it eventually recovers. The chart shows that the dip can be attributed mainly to lower real earnings for the highly qualified. If those made redundant or remaining unemployed can be re-employed quickly in equally good jobs, there’s no lasting damage. But otherwise recession erodes the value of these human assets.

Developing and publishing annual estimates for the human capital stock may even provide a useful corrective to the snap reactions one often gets after a natural disaster, which often present a nasty paradox of the destruction boosting economic growth because of the rebuilding required. But disaster is disaster, and the loss of lives is not only a terrible human cost but also the loss of a vital asset whose importance greatly outweighs the value of the buildings and roads.

The ONS estimates are based on the estimated lifetime earnings of the workforce, the outcome of investment in human capital through education and training. This is one of three possible approaches to measurement. One alternative measures expenditure on education and training, and the other measures educational attainment. Each has advantages and drawbacks. The main drawback of the one chosen here is that it assumes people are actually paid the value of their (marginal) contribution to economic output, and there are all kinds of reasons why that might not be true. Other assumptions concern the discount rate to apply to lifetime earnings, and labour productivity growth – the sensitivity analysis shows these do make quite a difference. Other shortcomings are that the estimates don’t take account of externalities which clearly exist, for example when the presence of other skilled people makes my own skill more valuable because employers will offer better jobs, nor of social effects of investment in human capital. The benefits of a high trust, civilised society are in a league of their own, compared to the mere economic benefits.

Nevertheless, it is very important that the ONS has undertaken this exercise, and I hope it will be updated annually. In [amazon_link id=”0691145180″ target=”_blank” ]The Economics of Enough[/amazon_link] I argue for the importance of measuring the economy’s comprehensive wealth, including human capital, to take proper account of the effect of today’s decisions on the future capacity of the economy. Without an estimate of all our assets, we simply can’t know whether the economy is on a sustainable path.

[amazon_image id=”0691145180″ link=”true” target=”_blank” size=”medium” ]The Economics of Enough: How to Run the Economy as If the Future Matters[/amazon_image]

Let’s ditch macroeconomics

Tim Besley has reviewed in Foreign Affairs three of my favourite books about economic development, [amazon_link id=”0691148198″ target=”_blank” ]Portfolios of the Poor[/amazon_link], [amazon_link id=”1586487981″ target=”_blank” ]Poor Economics[/amazon_link] and [amazon_link id=”052595189X” target=”_blank” ]More Than Good Intentions[/amazon_link]. His article is terrific, and Tim is too modest to plug his own recent book with Torsten Persson [amazon_link id=”0691152683″ target=”_blank” ]Pillars of Prosperity[/amazon_link].

Development economics is in good shape. The availability of new data sets, the use of randomized control trials and the bringing of empirical life to endogenous growth models where knowledge spillovers are vital have all contributed to its health. The growth outlook has become crucial for the developed economies, in order to escape from the present debt traps and longer term demographic constraints. We would do well to ditch conventional macroeconomics, which has failed, and look instead to applying the tools of modern development economics in our own back yards.

[amazon_image id=”1586487981″ link=”true” target=”_blank” size=”medium” ]Poor Economics: A Radical Rethinking of the Way to Fight Global Poverty[/amazon_image]