Attention: the scarcest resource

Herbert Simon, prescient in this as in so many things, was one of the first people to highlight the attention scarcity problem:

“…in an information-rich world, the wealth of information means a dearth of something else: a scarcity of whatever it is that information consumes. What information consumes is rather obvious: it consumes the attention of its recipients. Hence a wealth of information creates a poverty of attention and a need to allocate that attention efficiently among the overabundance of information sources that might consume it.”

From Designing Organizations for an Information-Rich World, in Martin Greenberger, [amazon_link id=”080181135X” target=”_blank” ]Computers, Communication, and the Public Interest [/amazon_link](1971 pp. 40–41).

The attention problem seems all the more acute post-financial crisis – why, when so many warning signals were available, and so much information about financial markets, did so few people foresee the crash? Not surprisingly, all thoughtful economists are now re-evaluating the standard assumptions about how people make economic decisions, in the light of what we can learn from psychologists and cognitive scientists. (This includes me, despite my blast in the previous post against the fashionable adoption of behavioural economics by anti-economists.)

The lessons look set to be fascinating, as this summary (pdf) of a recent workshop held at the Toulouse School of Economics shows. It’s well worth a look if you’re interested in this overlap between cognitive science and economics.

The researchers described the phenomenon of ‘inattentional blindness’, whereby people looking at a scene fail to see the obvious (the best-known example is the ‘invisible gorilla’ referenced in the title, and in a recent book called [amazon_link id=”000731731X” target=”_blank” ]The Invisible Gorilla[/amazon_link] by Chris Chabris and Dan Simons). ‘Seeing’ is not a matter of looking at an internal representation of the outside world, but rather depends on an active cognitive process of paying attention to certain things. The structure of the brain, whereby neurons at different levels compete with each other to move up to higher levels of the brain, determines what we pay attention to.

One consequence of this inbuilt scarcity is that attention can be guided by setting appropriate goals and stimuli. This can apply to helping an air traffic controller focus attention by suitable colour coding of visual screen displays – or potentially to helping financial regulators monitor developments in financial markets.

The workshop also heard some tantalising results on online advertising, viz:

  • Subliminal advertising and suggestion is ineffective;
  • Online advertising does work, with the amounts advertisers pay for slots at different locations on the screen a measure of the value of attention;
  • Offline ads are not more expensive than online ads, comparing the price of attention, as people spend many more minutes reading a newspaper or magazine than they do reading online;
  • Targeted online ads are often less effective than generic advertising;
  • Junk email could unravel the market for direct email advertising, but the collapse of the market could be averted by a message tax.

Also intriguing is the fact that the model of the brain currently accepted by the cognitive scientists features ‘winner-takes-all’ competition among neurons, a candidate for the kind of constrained optimisation techniques we use in economics.
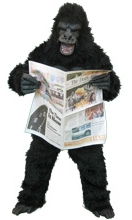
The Invisible Gorilla (courtesy of Chris Chabris)
Is behavioural economics just a fad?

I’m still reading Lionel Robbins’ classic [amazon_link id=”B0006DEH7I” target=”_blank” ]An Essay on the Nature and Significance of Economic Science[/amazon_link]. His definition of economics remains widely used: “Economics is the science which studies human behaviour as a relationship between ends and scarce means which have alternative uses.” (Chapter 1, Section 3)

Later in the book, he asks whether the resulting focus on relative valuations depends on particular psychological assumptions. The answer is a firm ‘no’:

“The borderlands of Economics are the happy hunting ground of minds averse to the effort of exact thought, and in these ambiguous regions, in recent years, endless time has been devoted to attacks on the alleged psychological assumptions of Economic Science. … Economics needs ‘rewriting from the foundations up’. As might be expected, the opportunity has not been neglected.” (Chapter 4, section 4)

This of course brought the present interest in behavioural economics to mind. There’s no shortage of people now claiming that economics needs rewriting utterly. Now, I’m as interested as the next economist in Daniel Kahneman’s new book, [amazon_link id=”1846140552″ target=”_blank” ]Thinking, Fast and Slow[/amazon_link]. Recently, I attended a fascinating workshop at the Toulouse School of Economics which brought together psychologists/cognitive scientists and economists precisely because the economic crisis has underlined the need for us to evaluate the compatibility of the assumptions we make in economics with the ever-growing knowledge of how the brain works (a summary of this workshop will be published soon & I’ll link to it then). Any economist who works, as I did for 8 years, on competition inquiries will know that the rules of thumb emerging from behavioural economics do reflect behaviour in some markets better than the standard rational choice models.

However, the Robbins challenge is a good one. There are some big issues about behavioural economics and the psychological experiments on which it is based, and these shouldn’t be overlooked in the current enthusiasm. One is that sometimes behavioural models are empirically more robust, but sometimes absolutely orthodox models do better with the data – why, and when? A related point is that the behavioural rules of thumb are no less arbitrary that the conventional assumptions about aspects of psychology, an argument made forcefully by Roman Frydman and Michael Goldberg in their recent book, [amazon_link id=”0691145776″ target=”_blank” ]Beyond Mechanical Markets[/amazon_link].

Equally, some of the phenomena described in every book on behavioural economics may not be as empirically robust as supposed, as so many reflect relatively small scale experiments among groups of US college students. For example, the results of the famous ultimatum game seem to vary from culture to culture, albeit in none does homo economicus reign.

So Robbins is too sweeping in his denunciation of fashionable psychology – indeed, he sets out some psychological assumptions in the book without appearing to be aware that they are assumptions that could potentially be disproved. But those quotable lines are a useful reminder not to get to carried away by fashion.

[amazon_image id=”1846140552″ link=”true” target=”_blank” size=”medium” ]Thinking, Fast and Slow[/amazon_image]

[amazon_image id=”0691145776″ link=”true” target=”_blank” size=”medium” ]Beyond Mechanical Markets: Asset Price Swings, Risk, and the Role of the State[/amazon_image]

Pretty poor fish

From [amazon_link id=”B002PNMILE” target=”_blank” ]An Essay on the Nature and Significance of Economic Science[/amazon_link] by Lionel Robbins (preface to 2nd edition, page ix):

An economist who is only an economist and does not happen to be a genius at his subject – and how unwise it is for any of to assume we are that – is a pretty poor fish. …[By} itself, Economics affords no solution to any of the important problems of life….an education which consists of Economics alone is a very imperfect education.

How true.

Next May I’m giving the Tanner Lectures at Brasenose, on the public responsibilities of economists and so have started re-reading (after a long gap) some of the classics. The Robbins, revised in 1935, stands up rather well in many ways.

A poor fish

The machines that ate all the jobs?

The admirable James Crabtree has reviewed very favourably (in the FT) the new e-book by Erik Brynjolfsson and Andrew McAfee, [amazon_link id=”B005WTR4ZI” target=”_blank” ]Race Against the Machine[/amazon_link]. He agrees with their argument that for the first time technology is not creating more jobs than it destroys. I haven’t read the book, but there can be few economists who know more about the mechanisms through which the adoption of the new technologies is reshaping firms and work, so this argument must be taken seriously. And I’d certainly agree with their further point that institutions and policies have not kept pace with the dramatic structural economic shifts caused by the technologies.

The best framework for thinking about adjusting to technical change is Will Baumol’s ‘unbalanced growth’ model (1967, 1993), which he originally applied to the arts and then healthcare and similar services. (I write about this in chapter 6 of [amazon_link id=”0691145180″ target=”_blank” ]The Economics of Enough[/amazon_link].) There are some sectors of the economy where productivity growth is inherently below average (musician, nurse) but the workers in those sectors need to have their pay grow more or less in line with the more productive sectors if social tensions are not to emerge. If the scope of the ‘non-productive’ sectors increases, new redistribution mechanisms are needed. Today’s technologies are causing exactly this dynamic, making a relatively few workers in some parts of the economy highly productive thanks to their complementarity with the machines, but creating a high share of economic output in services/products with public good-like characteristics, and extending the share of the economy accounted for by people working in slow productivity growth sectors.

As James ends his review: “Machines work for free but their benefits end up in someone’s pocket.”

So the book is certainly going to be worth reading even though only available in electronic format. Meanwhile, I look at the Occupy movements and seem to see the inevitable social reaction to socially unsustainable trends.

[amazon_image id=”B005WTR4ZI” link=”true” target=”_blank” size=”medium” ]Race Against The Machine: How the Digital Revolution is Accelerating Innovation, Driving Productivity, and Irreversibly Transforming Employment and the Economy[/amazon_image]

Cheer up! Or not?

The Observer today has an interesting article noting a sudden outbreak of optimism in new books published in the US – including Charles Kenny’s Getting Better[amazon_link id=”0465020151″ target=”_blank” ]Getting Better[/amazon_link], reviewed here, and Steven Pinker’s new book, [amazon_link id=”1846140935″ target=”_blank” ]The Better Angels of Our Nature[/amazon_link]. Why, the article asks, do we feel so bad if so many long term trends – in development, in diminishing violence – are actually improving?

Well, it isn’t a new question, and my answer is that the source of certain long-term improvements lies in short-term instability, which people in general don’t like, and particularly those who lose out. This was the theme of my 2001 book, [amazon_link id=”1587990822″ target=”_blank” ]Paradoxes of Prosperity[/amazon_link], which looked at the structural economic change resulting from new technologies. However, it was published in September 2001, not a great month for a book making this argument, for the obvious reason. So although I think the argument remains valid, the world is always a mix of the good and the bad, and no mere economist can give the verdict on how they balance.

[amazon_image id=”1587990822″ link=”true” target=”_blank” size=”medium” ]Paradoxes of Prosperity: Why the New Capitalism Benefits All[/amazon_image]