Kahneman, Keynes and unknown unknowns

I’m two-thirds through Daniel Kahenman’s [amazon_link id=”B005MJFA2W” target=”_blank” ]Thinking, Fast and Slow[/amazon_link], and will be posting a review early next week. It is one of the best books I’ve read all year, and it will change the way I think and work. There are not many books that change anybody’s mind about anything – most of us read to get support for the thing we already believe – so that’s already pretty high praise!

As a curtain-raiser, I wanted to quote from a section where Kahneman describes how he resolved a disagreement with Gary Klein, and advocate of ‘Naturalistic Decision Making’ who argued that the evidence indicated experts, thanks to their experience, are able to make intuitive and speedy decisions about problems that are better than the decisions non-experts would make. Kahneman (and his co-author Amos Tversky) argued that, on the contrary, experts are prone to all kinds of psychological biases including over-confidence and the failure to take account of evidence that contradicts their views, and do no better than non-experts.

In this book, Kahneman writes:
“We eventually concluded that our disagreement was due in part to the fact that we had different experts in mind. Klein had spent much time with fireground commanders, clinical nurses and other professionals who have real expertise. I had spent more time thinking about clinicians, stockpickers and political scientists trying to make unsupportable long-term forecasts. … He was more willing to trust experts who claim an intuition because, as he told me, true experts know the limits of their knowledge. I argued that there are many pseudo-experts who have no idea that they do not know what they are doing.” (p239)

Clearly Kahneman could add economists to his list. This isn’t the first call for economists to have more humility about the limits of what can be forecast, but it is one of the most forceful. More generally, this question of the context in which one is trying to make decisions seems to me to be an interesting aspect of behavioural economics – the kind of heuristics Kahneman describes in this book clearly apply in conditions of uncertainty with many ‘unknown unknowns’, but equally conventional and seemingly simple-minded economic models make very good predictions in other contexts; market/auction design is one of the success stories in economics. I think the boundary conditions are very interesting. This issue also underlines the urgent need to reintroduce uncertainty back into economics – as argued here recently, in a review of [amazon_link id=”0674057759″ target=”_blank” ]Capitalist Revolutionary: John Maynard Keynes[/amazon_link], the basic lesson we need to take now from Keynes.

[amazon_image id=”B005MJFA2W” link=”true” target=”_blank” size=”medium” ]Thinking, Fast and Slow[/amazon_image]
Age of technocracy?

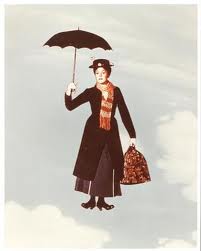
As a middle-aged, US-trained, European economist, I feel a natural sympathy for the middle-aged, US-trained, European economists floating into positions of power – a little like Mary Poppins, umbrella open, floating gently down from the sky to sort out the mess. Lucas Papademos, Mario Monti, Mario Draghi all seem like thoroughly decent, respected public servants, and one hopes fervently that their ascent will help restore calm to European financial markets, where inter-bank lending is drying up again.

The mini-trend does, however, raise the technocracy versus democracy question so powerfully raised by Daniel Bell in [amazon_link id=”0465097138″ target=”_blank” ]The Coming of Post-Industrial Society[/amazon_link] (in 1973):

“In a society which becomes increasingly conscious of its own fate, and seeks to control its own fortunes, the political order necessarily becomes paramount. Since the post-industrial society increases the importance of the technical component of knowledge, it forces the hierophants of the new society – the scientists, engineers and technocrats – either to compete with the politicians or become their allies. The relationship between the social structure and the political order thus becomes one of the chief problems of power in a post-industrial society.”

Written like a sociologist. But the book makes the point forcefully that the more complicated the economy and society, the greater the need for technical expertise in managing it, and the greater the tension with the growing presumption of democratic participation by all. Indeed, the technologies driving the social complexity are also driving the presumption that political participation by ordinary, non-expert folk will continue to grow. A financial system that has become a tangle of complex derivatives meets growing populism…. no signs that Bell’s dilemma is becoming any less acute, then.

A technocract parachuting in to the rescue

Lords of finance and lords of misrule

Reading about Italy’s ejection of Silvio Berlusconi in favour of economist Mario Monti, and in particular Mr Berlusconi’s reported mutterings that we would yet see that he was still in charge really through his supporters in the Italian parliament, I turned back to one of the best books about banking crises. That is Liaquat Ahamed’s brilliant history of the role of banking in the Great Depression, [amazon_link id=”009949308X” target=”_blank” ]Lords of Finance[/amazon_link]. As he notes in the introduction to the paperback edition I have, “Nothing brings home the fragility of the banking system or the potency of a financial crisis more vividly than writing about these issues from the eye of the storm.” He continues:

“Watching the world’s central bankers and finance officials grappling with the current situation – trying one thing after another to restore confidence, throwing everything they have at the problem, coping daily with unexpected and startling shifts in market sentiment – reinforces the lesson that there is no magic bullet or simple formula for dealing with financial panics. In trying to calm anxious investors and soothe skittish markets, central bankers are called upon to wrestle with some of the most elemental and unpredictable forces of mass psychology.”

The other lesson is that those who do not have the public interest at heart can fan those unpredictable forces of mass psychology too, in an adverse way. Mr Berlusconi still has the capacity to damage Italy and the euro, even out of office.

[amazon_image id=”009949308X” link=”true” target=”_blank” size=”medium” ]Lords of Finance: 1929, The Great Depression, and the Bankers who Broke the World[/amazon_image]

What have top policy people been reading?

I’m just back from a two day conference of senior policy people, gathered in an idyllic English country house to debate the post-crisis outlook for capitalism. There were people from other European nations and the US as well as the UK. It was interesting to find universal agreement in this group that some quite fundamental reforms are necessary, albeit disagreements over the specifics – a Tobin tax versus a Financial Activity Tax for example, or the mechanics for stopping the bankers’ bonuses merry-go-round. The tone of the debate about the responsibilities of the state via a vis markets was completely different from similar gatherings just two or three years ago.

It was also interesting to hear which books got name checked. They were:
[amazon_link id=”0691152632″ target=”_blank” ]Fault Lines: How Hidden Fractures Still Threaten the World Economy [New in Paper][/amazon_link] Raghuram Rajan
[amazon_link id=”0691152640″ target=”_blank” ]This Time Is Different: Eight Centuries of Financial Folly[/amazon_link] Reinhardt and Rogoff
[amazon_link id=”1846140552″ target=”_blank” ]Thinking, Fast and Slow[/amazon_link] Daniel Kahneman
[amazon_link id=”0140296727″ target=”_blank” ]The Truth About Markets : Why Some Countries are Rich and Others Remain Poor[/amazon_link]John Kay
[amazon_link id=”1408809737″ target=”_blank” ]Capitalism 4.0: The Birth of a New Economy[/amazon_link] Anatole Kaletsky
[amazon_link id=”B005WTR4ZI” target=”_blank” ]Race Against The Machine: How the Digital Revolution is Accelerating Innovation, Driving Productivity, and Irreversibly Transforming Employment and the Economy[/amazon_link] Erik Brynjolfsson and Andrew McAfee
[amazon_link id=”0691153191″ target=”_blank” ]The Darwin Economy: Liberty, Competition, and the Common Good[/amazon_link] Robert Frank

It’s a great selection – how encouraging that these influential chaps (yes, mainly men of course) are reading seriously. Fingers crossed for action now.

Keynes’s real lesson for today

Since the onset of the crisis in 2008, it has been natural to look to past masters for wisdom and a few names have recurred more than most: [amazon_link id=”0071592997″ target=”_blank” ]Hyman Minsky[/amazon_link] for his analysis of the inherent instability of finance, [amazon_link id=”0199535701″ target=”_blank” ]Karl Marx[/amazon_link] for predicting the inherent instability of capitalism per se, and above all John Maynard Keynes for all round brilliance about the economy in crisis: what should our governments and central bankers actually be doing? However, there have been at least as many interpretations of Keynes as books written about him, and one might imagine there is no room for another on the crowded shelves of that new section in our bookstores, ‘Economic Crisis’. That would be wrong. Roger Backhouse and Bradley Bateman have written a new book, [amazon_link id=”0674057759″ target=”_blank” ]Capitalist Revolutionary: John Maynard Keynes[/amazon_link], which is a brilliant summary of both what Keynes said about his own times, how his work influenced policy at different times in the past, and how to interpret him for our times. As they put it early in the book, there is a Keynes for good times and bad times.The book is a terrific read, marvellously clear, and will illuminate this great economist for both experts and general readers.

They have one underlying message as well, which is that we should take above all from Keynes the lesson that there is a moral dimension to policy as well as a technical one.  As he put it: “No man of spirit will consent to remain poor if he believes his betters to have gained their goods by lucky gambling.” (Quoted here p59). One chapter in Capitalist Revolutionary explains Keynes’s deep engagement with moral philosophy, starting as an acolyte at Cambridge of G.E. Moore. This, they say, is the real relevance of his work to the present crisis: economists must re-learn how to discuss morals, and the nature of the whole economic system. The authors’ recent New York Times article summarised this line of argument.

The book does a great job of setting Keynes’s influence in the context of his times. In the 1930s, “There was a deep-seated change in attitudes toward government policy that was the result of many political and social factors, to which Keynes’s name came to be attached.” (p30). It shows that [amazon_link id=”0230004768″ target=”_blank” ]The General Theory of Employment, Interest and Money[/amazon_link] was so important because it is the lens through which subsequent generations see previous work and also provided a framework for a subsequent explosion of creative thinking by other economists. That framework proved flexible, and Keynes himself encouraged younger economists to take different paths, and hence the many interpretations now of what it is to be ‘Keynesian’. What’s more, Keynes insisted that macroeconomics was contingent, that it had no truths that stood for all time. Earlier in his career, although clear that “capitalism was an imperfect machine that needed to be maintained and updated if it were to continue to work to meet society’s needs” (p56), he had hunted for a ‘magic formula’ to solve the economic crisis. But by the time of the General Theory he had concluded that the radical uncertainty that is the most important feature of the world, and the importance of the specifics of time and place, meant there could be no noisy certainty about simple solutions.Indeed he embraced ambiguity.

Would Keynes share either the certainty of one branch of macroeconomics that what the world needs now is bigger government deficits to maintain effective demand, or of the other branch that what we need is to eliminate deficits to keep real interest rates low and encourage investment? The authors are clear that he was more cautious about budget deficits than the economists labelled ‘Keynesian’ who advocated fine-tuning in the 1960s and 70s. He thought the government should not borrow for consumption, but only to finance investments, so the deficit would ultimately pay for itself. He scaled back William Beveridge’s initial plans for the welfare state to ensure it was affordable. By the end of the book, however, it is clear that trying to read off an answer to today’s problems from The General Theory – never mind from the other works of a man who was not afraid to change his mind – is a meaningless exercise. Keynes himself would have wanted to know the detail of our times, and would know that any given policy might or might not work depending on how it affected people’s expectations, inherently unforecastable.

This relatively short book also gives a tremendous flavour of the richness of Keynes’s interests, the importance he attached to the arts as the meaningful part of life, his idiosyncratic career as a mix of policy expert, academic, journalist, bohemian and speculator. I would say that if you’re only going to read one book about Keynes, it should be this one. I really enjoyed it and learnt a lot.

[amazon_image id=”0674057759″ link=”true” target=”_blank” size=”medium” ]Capitalist Revolutionary: John Maynard Keynes[/amazon_image]